Labour Day came and went with no dramatic changes to lumber prices.
Sentiment throughout the marketplace stayed where it had generally been for
the past long while: a cautious approach and just-in-time buying. Supply
remained on the tighter side, as the year moved steadily into the slow-down
time of winter. Conversations ranged to the latest announcements of trade
restrictions and penalties.
Given that these are forward-dated for several weeks, most held to the hope
that a resolution would be found. The northeast was absolutely hammered by
some incredible storms, which put a total stop to whatever construction
activity was ongoing.
Expectations are for further quite turbulent weather through the rest of
this year and potentially into spring.
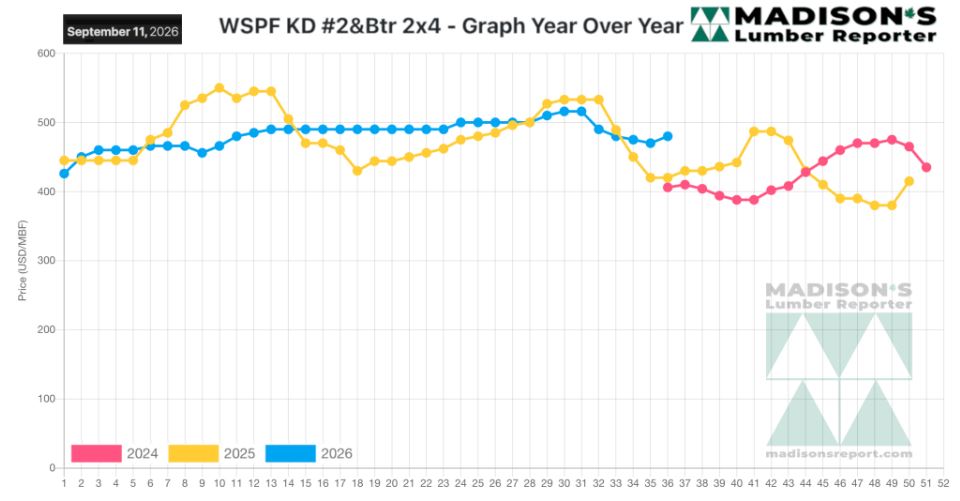
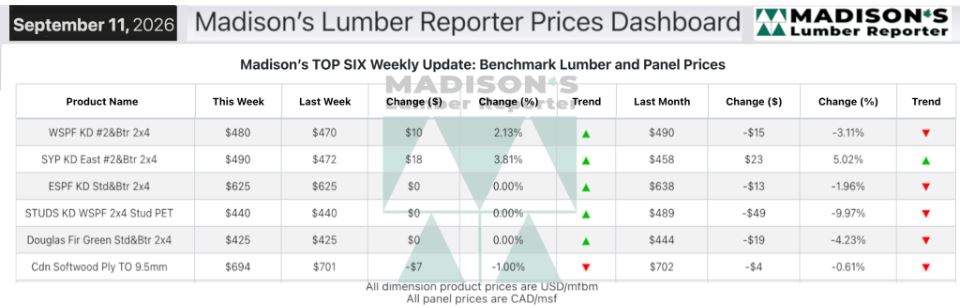
In the week ending September 11, 2026, the price of benchmark softwood
lumber item Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) was US$480 mfbm.
This was up +$10, or +2%, from the previous week when it was $470, said
weekly forest products industry price guide newsletter Madison’s Lumber
Reporter.
That week’s price was down -$10, or -2%, from one month ago when it was
$490.
Compared to the same week last year, when it was US$420 mfbm, the price of
Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) for the week ending September 11,
2026 was up +$60, or +14%.
Compared to two years ago when it was $406, that week’s price was up +$74,
or +18%.
Tariff turbulence, pokey pricing, and post-vacation sluggishness kept demand
subdued.
KEY TAKE-AWAYS:
• Western-SPF traders in the United States reported business overall
continued to feel disjointed.
• Buyers rolled on with their need-based strategies; as the obvious lack of
market direction reinforced their cautious approach.
• Tight overall supply kept prices firm in most cases.
• In Canada, Western-SPF sellers also felt a broad sense of hesitation in
the market.
• Eastern-SPF suppliers described a strong sideways slant to business as
post-Labour Day sales failed to launch.
• Torrential rains on the region caused floods and put a halt to activity at
scores of jobsites.
• Eastern sawmills showed increasing resistance to deeper counter-offers as
the market appeared to stabilize more broadly.
• The recent positive trajectory of Southern Yellow Pine prices persisted.
• Overall perception was the southern species would not get much cheaper
from here to the end of the year.
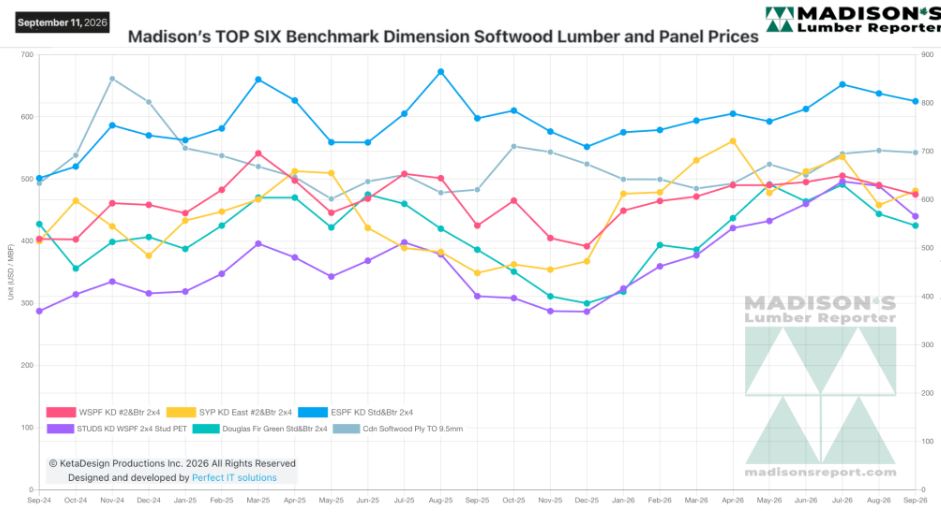
MADISON’S BENCHMARK TOP-SIX SOFTWOOD LUMBER AND PANEL PRICES: MONTHLY
AVERAGES
Source: madisonsreport.com
More Reports:


