Many players in the North American construction framing dimension softwood
lumber market were preoccupied with the results of the US mid-term
elections.
Much speculation circulated about what the changes to US representatives
would mean for the general economy and for home building specifically. At
the same time the huge North American Wholesale Lumbermen’s Association
(NAWLA) was held, so a large number of players were away from their desks
hobnobbing.
Demand for solid wood products remained quite soft as sentiment continued in
the very cautious approach of the past couple of years. Prices maintained a
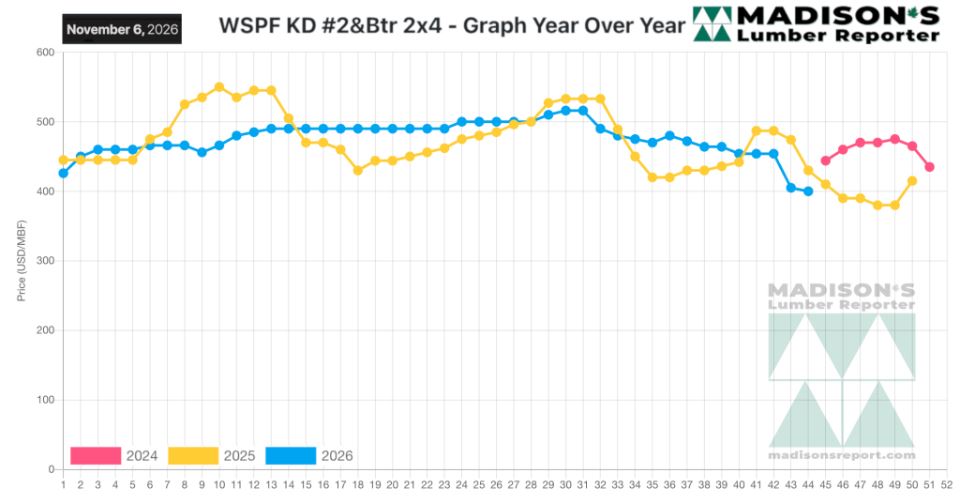
nice steady trendline over the course of this year and in comparison to the
previous two years,
which at least provided some consistency for industry folks to make their
plans going forward.
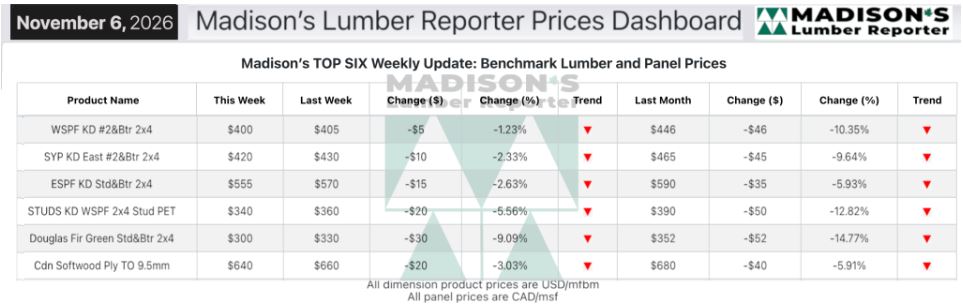
In the week ending November 06, 2026, the price of benchmark softwood lumber
item Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) was US$400 mfbm. This was
down -$5, or -1%, from the previous week when it was $405, said weekly
forest products industry price guide newsletter Madison’s Lumber Reporter.
That week’s price was down -$46, or -10%, from one month ago when it was
$446.
Compared to the same week last year, when it was US$487 mfbm, the price of
Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) for the week ending November 06,
2026 was down -$33, or -7%.
Compared to two years ago when it was $402, that week’s price was up +$52,
or +13%.
Lumber prices continued to drift lower in most categories as scads of
players were away from their desks to attend this year’s NAWLA Traders
Market.
 KEY TAKE-AWAYS:
• Many offices were quieter as scads of players absconded from their desks
to attend the annual NAWLA Traders Market.
• Demand for Western-SPF in the US remained shaky and unlikely to improve as
weather in most key markets shifted to winter.
• Trucking remained a challenge especially in Northwest regions where
equipment availability and high freight rates stood out.
• November kicked off with little fanfare for Western-SPF sellers in Canada
as buyers were content to mostly sit on the sidelines.
• For Eastern-SPF players the market was described as fragmented.
• In the East, supply and demand varied considerably by grade, source,
destination, and side of the border.
• Producers of Southern Yellow Pine commodities started drawing some lines
in the sand to prevent further falling prices.
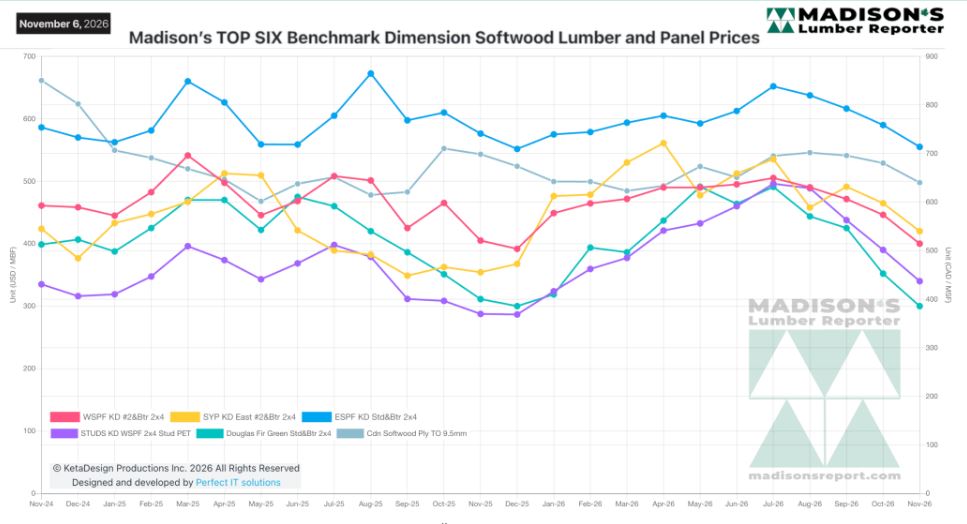
MADISON’S BENCHMARK TOP-SIX SOFTWOOD LUMBER AND PANEL PRICES: MONTHLY
AVERAGES
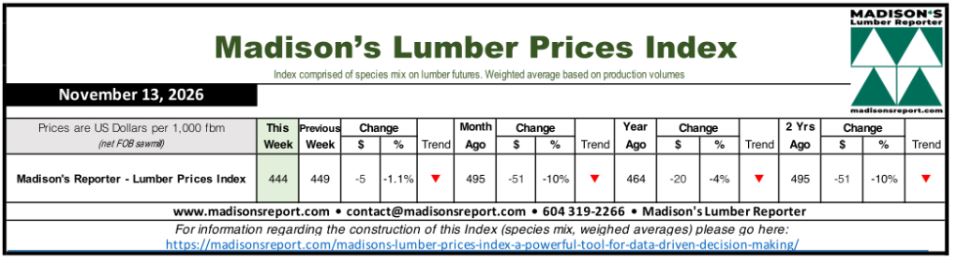
Madison’s Lumber Prices Index Nov 13, 2026: US$444 mfbm
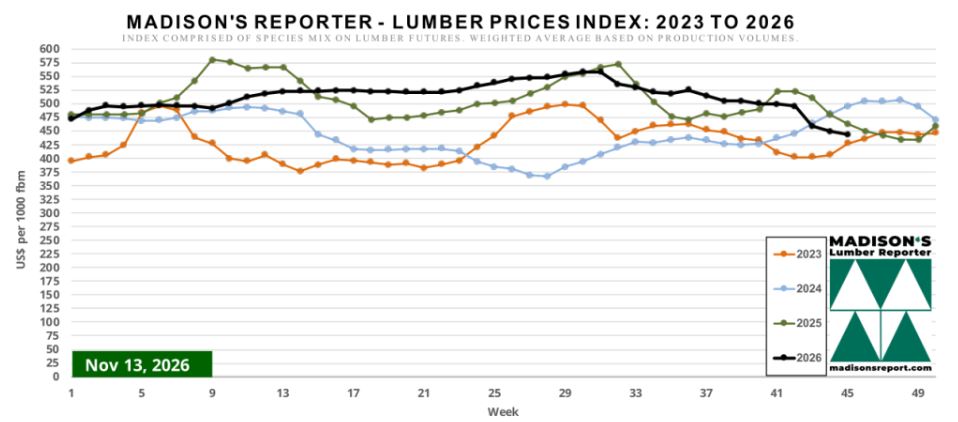
The Madison’s Lumber Prices Index for the week ending Nov 13, 2026 is:
US$444 mfbm
This is down -1%, or -$5, from the previous week when it was US$449.
This is down -10%, or -$51, from one month ago when it was US$495.
Source: madisonsreport.com
More Reports:


