As the annual seasonal cycle of housing construction plodded on into winter
weather, customers continued to be conservative with the lumber purchases.
The now long-term practice of just-in-time buying remained the norm. Lumber
sales volumes remained muted as they have been for the past three years.
Source Lumber
Discussions revolved around external factors like macro-economic conditions
and rising costs, particularly freight. Having no visible reason to change,
most players held on to whichever opinions they had for most of this year;
whether bearish or otherwise. What will happen at the start of next year is
a big mystery for all.
Attitudes generally are; to not make any big leaps or sudden movements. A
sentiment of caution reigned until future events will provide more clarity.
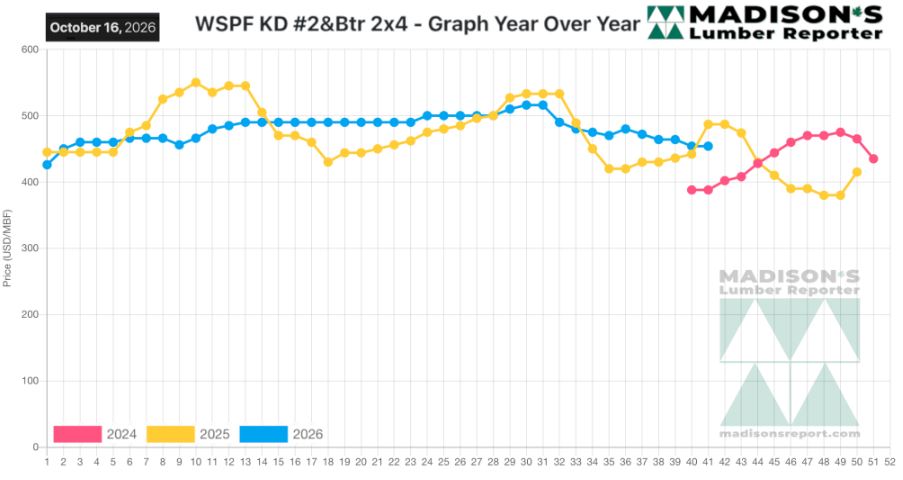
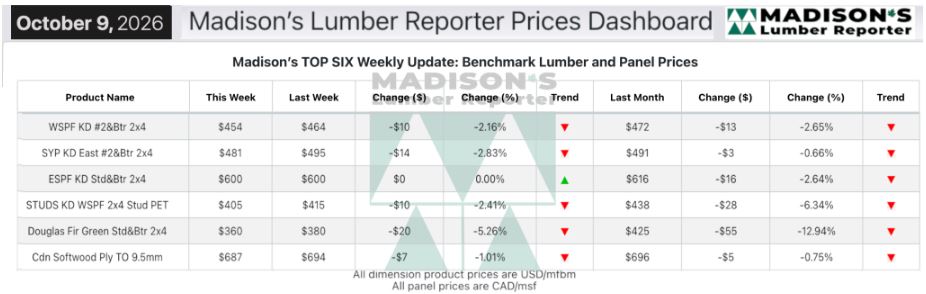
In the week ending October 23, 2026, the price of benchmark softwood lumber
item Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) was US$454 mfbm. This was
flat from the previous week, said weekly forest products industry price
guide newsletter Madison’s Lumber Reporter.
That week’s price was down -$18, or -4%, from one month ago when it was
$472.
COMPARED TO THE SAME WEEK LAST YEAR, WHEN IT WAS US$487 MFBM, THE PRICE OF
WESTERN SPRUCE-PINE-FIR 2×4 #2&BTR KD (RL) FOR THE WEEK ENDING OCTOBER 23,
2026 WAS DOWN -$33, OR -7%.
COMPARED TO TWO YEARS AGO WHEN IT WAS $402, THAT WEEK’S PRICE WAS UP +$52,
OR +13%.
Trends established so far in October were evident again as demand in
all regions showed signs of misfiring.
 KEY TAKE-AWAYS:
• Buyers were content to carry lean inventories and showed zero urgency as
they had no trouble getting what they needed.
• Sellers of Western-SPF in the United States increasingly courted business
to move more stubborn sizes.
• In Canada buyers of Western-SPF remained circumspect and commodity prices
continued to follow entrenched patterns.
• Eastern-SPF players reported conflicting signals, as asking prices were
all over the place.
• A few Eastern Canadian sawmills tried to pump up their numbers, but failed
due to weak market dynamics and subpar takeaway.
• Several key Southern Yellow Pine items sold at below breakeven levels for
sawmills.
• The overall sentiment of Eastern Stocking Wholesalers was one of weakness,
however there were mixed reports depending on the source.
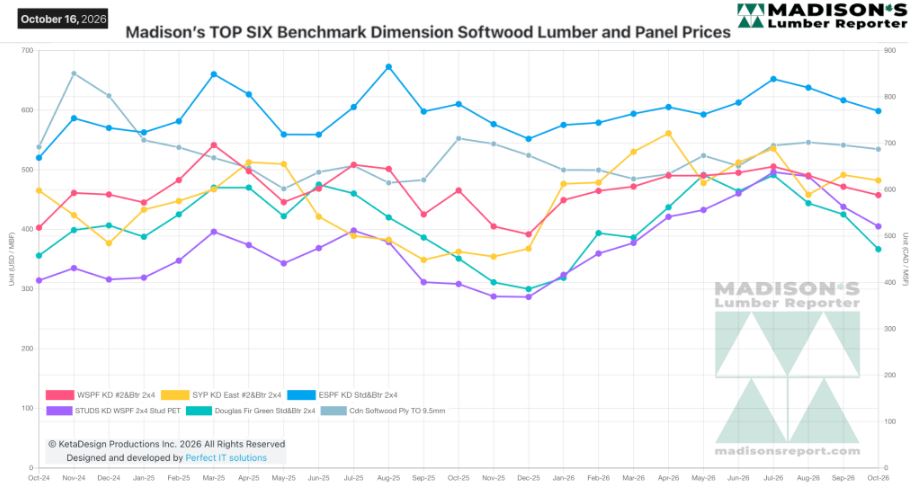
MADISON’S BENCHMARK TOP-SIX SOFTWOOD LUMBER AND PANEL PRICES: MONTHLY
AVERAGES
Madison’s Lumber Prices Index
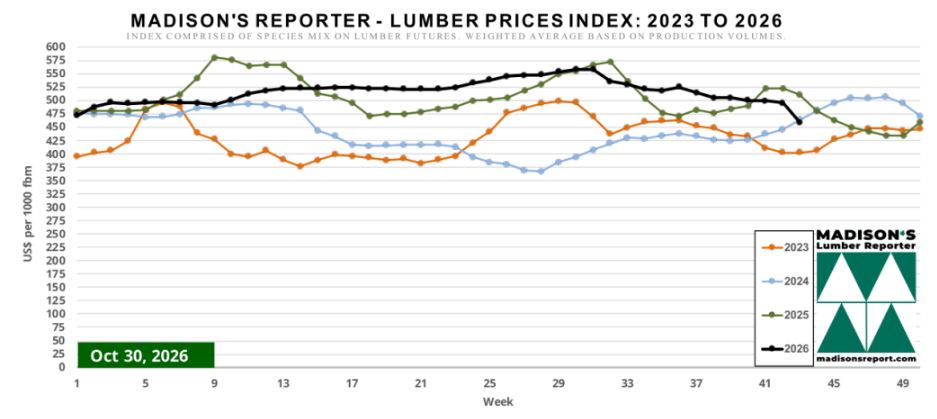
The Madison’s Lumber Prices Index for the week ending Oct 30, 2026 is:
US$459 mfbm
This is down -7%, or -$36, from the previous week when it was US$495.
This is down -8%, or -$40, from one month ago when it was US$499.
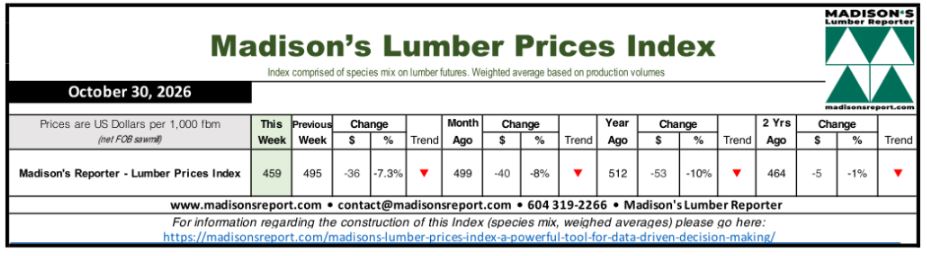
Source: madisonsreport.com
More Reports:


